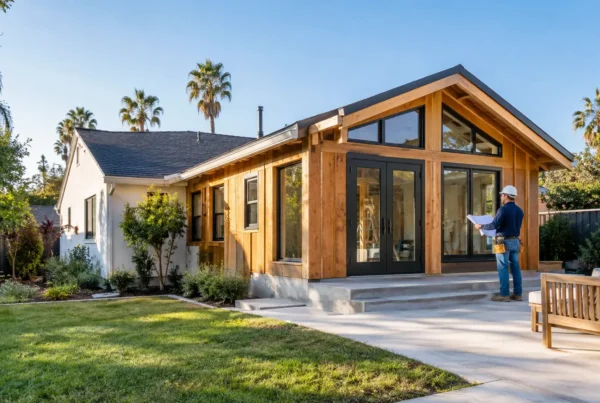
A backyard ADU can create room for family, rental income, a home office, or a long-term investment in your property. But before choosing finishes or finalizing floor plans, homeowners need a clear ADU finance strategy that matches the project scope, timeline, and household budget. The right funding approach gives you control over the work. The wrong one can create delays, change orders, or a project that never reaches the finish line.
For homeowners in Los Angeles and Orange County, financing an ADU is not just about covering construction costs. It is about paying for the full path from early feasibility to permits, site work, inspections, and final turnover. A dependable contractor can help define that path before you apply for financing, so the numbers you present to a lender reflect the work your property actually requires.
What ADU Finance Needs to Cover
A common mistake is comparing loan amounts only to a neighbor’s advertised ADU price. Every property has different conditions. A detached unit built on a flat, accessible lot is not priced like a garage conversion with major structural upgrades, utility relocation, or a challenging permit path.
Your financing plan should account for design and engineering, surveys or site investigation where needed, permit fees, utility work, demolition, foundation or structural modifications, construction labor, materials, inspections, and a contingency reserve. If the ADU will be rented, you may also want to budget for appliances, landscaping, fencing, separate access improvements, and insurance adjustments.
A detailed project estimate matters here. It helps you distinguish between a realistic construction budget and a low starting number that excludes necessary work. Good planning protects your financing decision because you know what is included, what is still being evaluated, and where the project has flexibility.
Common Ways to Finance an ADU
There is no single best loan for every homeowner. The right option depends on available equity, credit profile, income, current mortgage terms, how quickly you need to start, and whether you plan to occupy or rent the ADU.
Home Equity Loan or HELOC
A home equity loan provides a lump sum, usually with a fixed interest rate and set repayment schedule. This can work well when your project has a clearly defined budget and you prefer predictable monthly payments.
A home equity line of credit, often called a HELOC, gives you access to a revolving credit line secured by your home equity. Because construction expenses are paid in stages, a HELOC can be useful for homeowners who want to draw funds as work progresses. The trade-off is that rates may be variable, and the payment structure can change after the draw period ends.
Both options can make sense when you have substantial equity and want to preserve a favorable first-mortgage interest rate. However, your home secures the financing, so borrowers should be comfortable with the repayment obligation before moving forward.
Cash-Out Refinance
A cash-out refinance replaces your current mortgage with a new, larger loan and provides the difference as cash. It can offer one payment rather than separate mortgage and equity-loan payments.
This option deserves close review. If your existing mortgage has a low rate, refinancing the entire balance could cost more over time even if the ADU financing itself seems attractive. It may fit homeowners who can improve their overall loan terms or who need a larger amount than a second-lien product can provide. A lender can show the payment difference, closing costs, and total borrowing cost under several scenarios.
Construction Loan
A construction loan is built around the project schedule. Funds are typically released in draws after defined milestones, such as foundation completion, framing, rough mechanical work, or final completion. This structure can be a strong fit for a ground-up ADU or a complex conversion with significant structural work.
Construction lending usually requires more documentation than a standard home equity loan. Lenders may ask for plans, permits or permit status, a signed construction contract, a detailed scope, contractor licensing information, and an appraisal based on the completed property. The extra review can take time, but it can also create clearer financial controls throughout the build.
Some construction loans convert into permanent financing once the project is complete. Others must be paid off or refinanced after construction. Confirm that transition early. It affects your long-term payment and prevents surprises at closeout.
Personal Loans and Other Unsecured Financing
An unsecured personal loan does not use your house as collateral and may close faster than property-secured financing. It is generally better suited to smaller scopes, such as interior finishes, a limited garage conversion component, or a gap between savings and a larger loan.
The downside is usually a higher interest rate, shorter repayment term, and lower borrowing limit. For a full ADU build, unsecured debt may not provide enough capital or may create a monthly payment that is too high for the household budget.
Start With the Property, Not the Loan Application
Before selecting a lender, confirm what your property can support. Zoning rules, setbacks, access, utility capacity, existing structures, slope, drainage, and fire-safety requirements can all influence design and cost. In many cases, the most valuable early step is a feasibility discussion with a qualified contractor who understands local construction conditions and permit-oriented coordination.
This is especially important for garage conversions. An existing garage may look like ready-made square footage, but the building may need foundation work, framing upgrades, insulation, new windows, plumbing, electrical upgrades, or a sewer connection. A clear site review keeps you from financing an assumption rather than a buildable plan.
At RD Fast Construction, the goal is to give clients a practical scope that connects their vision to the work required for a durable, code-conscious result. That includes identifying decisions that affect cost early, when they are easier to manage.
Prepare Documents Lenders Can Use
Lenders make decisions based on financial qualifications, but a well-documented project helps them understand the purpose and value of the request. Once your ADU plan is developed, organize the project information into a straightforward package.
This often includes preliminary plans, a written scope of work, contractor estimate, anticipated schedule, permit information when available, proof of contractor licensing and insurance, and photos or records that show existing site conditions. For rental-focused projects, lenders may also want to understand expected rental income, although their rules for counting future ADU income vary.
Do not promise a lender that a permit will be issued by a certain date unless that approval is already in hand. Permitting timelines can change based on corrections, agency workload, utility requirements, and project complexity. A realistic schedule builds confidence and gives your construction team room to manage the process properly.
Build a Budget With a Real Contingency
Even careful planning cannot eliminate every unknown behind walls, under slabs, or in older utility systems. A contingency is not a sign of poor management. It is a responsible reserve for conditions that could not be fully confirmed before construction.
The appropriate amount depends on the project. A straightforward new detached ADU on a well-understood site may carry less uncertainty than a conversion in an older structure. Your contractor should explain which assumptions are included in the estimate and which conditions may require additional work if discovered.
Avoid spending every approved dollar on the construction contract alone. Keep room for lender fees, interest during construction if applicable, owner-selected upgrades, furnishings, and unexpected site conditions. If you expect rental income to help support repayment, be conservative about when that income will begin. Construction completion, inspections, certificate requirements, furnishing, and tenant placement do not always happen on the same day.
Compare the Total Cost, Not Just the Rate
A lower advertised interest rate does not automatically mean lower-cost financing. Compare origination fees, appraisal charges, closing costs, draw administration fees, prepayment rules, rate adjustments, and the repayment term. Also compare the monthly payment during construction with the payment after the loan converts or enters repayment.
Ask lenders how they handle construction draws, what documentation they require at each stage, and whether inspections are required before funds are released. A draw process that does not align with your contractor’s schedule can slow material ordering and trade coordination. Clear expectations keep the project moving efficiently without cutting corners.
Make Financing Support the Build
The strongest ADU finance plan is one that supports disciplined construction from the first site review through final inspection. It gives you enough capital for the real scope, a reserve for reasonable uncertainty, and a payment structure that still works after the unit is complete.
Before you commit, bring your lender’s questions, your contractor’s estimate, and your own long-term goals into the same conversation. When the funding plan and construction plan are built together, you can move forward with greater confidence and keep your new living space focused on the people and opportunities it is meant to serve.